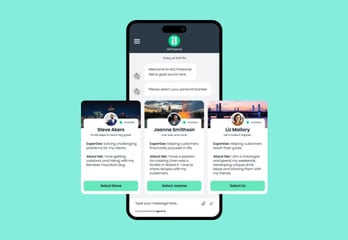
A bank with nearly 100 branches used Lynq® to extend personal banking relationships beyond the branch through persistent messaging and proactive outreach.
In the bank’s study, customers who had a personal banker for at least two years held 24% higher average balances, were three times more likely to have both checking and loan accounts, and were half as likely to call the call center.
What is digital relationship banking?
Digital relationship banking gives account holders ongoing access to a banker or team through digital channels while preserving the context of the relationship over time.
For this institution, that meant giving customers a convenient way to contact a familiar banker, continue conversations asynchronously, and receive proactive guidance without visiting a branch. It extended the personal service of a physical location into a virtual branch experience.
Relationship banking beyond the branch
For more than a century, this bank has built its reputation on personal service for individuals and businesses. As customer expectations changed, the institution launched an initiative to extend those relationships beyond its nearly 100 physical branches.
With Lynq, customers could contact their personal banker through persistent messaging and receive a response when the banker was available. Bankers could also reach out proactively through push notifications, creating new opportunities to offer guidance, discover unmet needs, and continue the relationship digitally.
Why customers valued access to a familiar banker
Customers responded positively to the ability to remain connected with a banker they knew. Their unsolicited feedback emphasized personal choice, convenience, and the value of continuing an established relationship.

Much like an in-branch visit, customers often chose to wait for their personal banker even when another banker was available immediately. The institution balanced responsiveness with the value of an ongoing personal relationship.
The business impact of a personal banking relationship
The bank compared customers who had a personal banker for at least two years with customers who did not. The study found that customers with a personal banker were:
- 2× more likely to have checking and savings accounts
- 24% higher in average balance holdings
- 1.4× more likely to have checking and CD accounts
- 3× more likely to have checking and loan accounts
- 3× more likely to use bill pay
- 5× more likely to use Zelle®

Additionally, 66% of customers with a personal banker had more than one deposit account, compared with 27% of customers without one. Customers with a personal banker were also half as likely to call the call center.
What this meant for bankers
The service gave bankers a practical way to manage their customer relationships digitally. Since launch, the bank reported zero elective attrition among bankers using the system.
“We have created a level of service that feels almost nostalgic, like coming into the branch and seeing the familiar face of a banker who has served you for years.”
The bank credits the program’s success to its bankers, training, corporate values, and commitment to lasting relationships. The technology provided a way to extend that service beyond the branch.
How Lynq supported the strategy
Lynq helped the institution:
- Continue customer relationships through persistent messaging
- Reach customers at relevant moments through proactive outreach
- Preserve relationship context across ongoing digital conversations
- Extend personal service beyond the branch through a connected digital experience
What this case study shows
Within this institution, customers with a longstanding personal banker relationship showed higher balances, broader product adoption, greater digital engagement, and lower call-center use. These institution-specific findings show how personal relationships and digital access can work together, but they do not guarantee identical outcomes for every institution.